“Beta, bas ek achhi naukri mil jaaye. Fir zindagi set hai.”
One sentence. One plan. One whole generation.
Nobody mentioned it came with an expiry date.
That line is the foundation of the Indian hard-working family dream. It echoes in every household, at every dinner table, in every parent's wish. And for most of us, it was not one option among many. It was the only plan we ever saw.
The plan that worked for our parents
It went like this.
Study hard. Get a stable job. Buy a house. Take care of your parents. Raise your kids. And then retire quietly.
Safe. Predictable. Respected.
Our parents followed it. So did our uncles and aunties. And it worked for them, or at least it appeared to.
So we inherited it with full faith. Nobody checked whether the plan had been updated for the prices we would actually face.
What the safe path looks like today
Picture the life. Although for many of us, picturing is not required.
A decent 9-to-6 job. Somewhere between ₹40,000 and ₹80,000 a month. Rent, or an EMI. You try to put aside ₹2,000 to ₹5,000 in the months that allow it.
Some traditional insurance. Maybe a PPF. Maybe a fixed deposit.
Life looks stable.
Then the calendar arrives. Diwali gifting. School fees. Three wedding invitations in one month. A medical expense. House repairs.
And one relative with the same advice for every situation:
“Beta, one more policy lena safe rahega.”
Every family has that one uncle whose answer to everything is a policy. New job, policy. New baby, policy. Your savings, also policy — locked for twenty years, growing slower than the school fees.
By the time the month closes, your savings are either locked in something low-return or already spent.
The bank balance never quite grows. You are working harder. You are earning more. And you still feel behind.
Does this sound familiar? You are not alone.
The mask we all wear
From the outside, you look completely sorted.
- Formals to work
- Your child in an English-medium school
- Family vacation photos on Instagram
- A car, on EMI
- A flat, on EMI
- And you nod along when people discuss SIPs, even if you have not started one
But inside, there is anxiety. There is some debt. And there is that one thought that shows up at eleven at night:
“I don't know if I can handle one more financial emergency.”
That is the hard-working family illusion. We look fine. We feel tired. We believe we are moving up, when really we are running in place.
This is not an income problem
Most people assume they are stuck because they do not earn enough. So they wait for the raise, convinced that the raise is the rescue.
I have watched what the raise actually does. A man gets promoted after twelve honest years. Bigger title, higher CTC, glass partition. Within months there is a new car on a seven-year EMI, a bigger flat booked with a personal loan, and a holiday on the credit card.
Salary up 25%. Expenses up 60%. Peace of mind down 90%.
One promotion, three movements
Show as a table
| Salary | up 25% |
| Expenses | up 60% |
| Peace of mind | down 90% |
More income poured into the same thinking does not create freedom. It just upgrades the cage.
Saving money and growing money are two different things
This is the part nobody explained to us.
Saving is good. Saving alone will not make you wealthy.
If your money sits in a 5% fixed deposit while inflation runs at 7%, you are losing money — safely, politely, on schedule.
Look at where most hard-working families park everything.
- FDs barely beat inflation
- Traditional insurance returns roughly 4 to 5%
- Gold is unstable and generates no monthly cash flow
- Real estate needs maintenance and taxes, and cannot be sold quickly when you need cash
The four places the money sits, against the 7% line
Show as a table
| Inflation | 7% a year |
| Fixed deposits | 5% a year |
| Traditional insurance | roughly 4 to 5% |
| Gold | no return figure given |
| Real estate | no return figure given |
The result is strange and painful. You work very hard. Your money does not.
And there is a second reason we stay here. Society only celebrates what it can see. A car is seen. A bigger house is praised. Nobody claps when you increase your SIP. Nobody posts a selfie with their emergency fund.
“Bas thoda save karna hai” is not a goal
Ask most people about their financial goal and you will hear this, or “Ghar lena hai”, or “Shaadi karani hai”.
Those are wishes. Warm, sincere wishes. But you cannot aim at them.
A goal sounds different.
An amount, and a year
“I want ₹50 lakhs by 2035 for my daughter's education.”
An age, and a figure
“I want to retire at 55 with ₹3 crores.”
An income, and a date
“I want ₹25,000 a month of passive income in five years.”
You can only hit a target you can actually see.
A maid in Mumbai did it better than her employer
In Mumbai, a maid invested ₹5,000 a month in mutual funds for eighteen years, on her employer's advice. She retired with over ₹35 lakhs.
Where her ₹35 lakh came from
Show as a table
| Her own money (₹5,000 × 12 × 18) | about ₹10.8 lakh |
| What the eighteen years added | about ₹24.2 lakh |
| At retirement | over ₹35 lakh |
Her employer kept changing cars and had nothing saved.
Why did it work for her? She did not overthink it. She started, and she stayed consistent.
It is not about how much you earn. It is about what you do with it.
Simple tools that work on a modest salary
You do not need a new income to begin. You need a few plain habits. Start with one, and stack the rest later.
- A 30-day expense tracker. Not an app — a ₹20 notebook. Write down every expense, even the ₹20 chai and the ₹89 UPI payment. At month-end, sort them into essentials, lifestyle and unnecessary. Awareness is what builds control.
- Cut 10% without pain. Forgotten subscriptions, food delivery instead of home cooking, branded groceries where generic works, impulse buys. You do not have to suffer to save.
- Start a SIP, even at ₹500. If you can order a pizza once a month, you can invest. Pick a simple fund, automate it, and leave it alone for three to five years.
- Separate your accounts. One for salary and bills, one for investments, one for the emergency fund. When all the money sits together, it feels like more, so we spend more.
- Protect before you grow. Term insurance, not a traditional policy. Health insurance of at least ₹5 to ₹10 lakh. One hospital bill can erase years of saving. Insurance is protection, not investment.
- Find your Enough Number. Ask what monthly income would make you feel peaceful — not rich, safe. Maybe ₹60,000. Maybe ₹1.2 lakh. Multiply by twelve. Once you know that number, other people's cars stop setting your targets.
Before you start, drop the guilt
If some of this stung, read this slowly.
You did what you could, with what you knew. You were not lazy and you were not careless. You were simply never taught the truth.
You are not behind. You are awake.
That is the whole point of a wake-up call, and it is the reason I wrote The Money Wake-Up Call.
Your one move today
Do not wait for a big transformation. Choose one small thing this week.
Tonight, take any notebook and write down every rupee you spent today. Just today. Then do it again tomorrow.
Thirty days of that notebook will teach you more about your money than thirty years of “bas ek achhi naukri mil jaaye”.
One honest idea a week.
A short letter drawn from the books — one idea, and one small thing worth trying this week.
No spam. Your email is never sold or shared, and you can leave whenever you like.
Read next
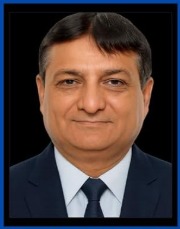
Hitesh Lakhani
Author of The Money Wake-Up Call, The Energy Wake-Up Call, The Relationship Wake-Up Call and The Business Wake-Up Call. He writes about the decisions people actually face — money, energy, relationships and business — without the jargon.
Read the book